
Can you rely on your government to fund your retirement?
Obvious answer? No.
..but maybe none of us are truly aware of what that means, because we don’t seem to be taking this retirement thing seriously until we’re in our 50s and realizing that retirement is only about 10 – 15 years away, and we can’t actually afford it.
Here’s what Canadians can expect:
The MAXIMUM we can get from CPP and OAS is:
CPP = $1012.50 a month if you retire at age 65
OAS = $550.99 a month
Grand total: $1563.49 if you qualify for maximum CPP & OAS (which is hard to do)
If you’re REALLY hard up and have no money at all, then there’s also GIS which is guaranteed income supplement, but you need to be really making next-to-nothing and to have nothing saved to qualify.
(I myself have taken dividends as an income, so I don’t qualify, which makes me all the more aware that I am not to rely on the Canadian government for any money.)
We simply can’t rely on the government for our retirement.
Even more telling?
” In Canada, 72% of us have no corporate pensions.
Half of people have no RRSPs, and the half that do have an average of $42,000.
[…] 51% of Canadians can’t lay their hands on $10,000 in the event of an emergency.
And yet about 75% of Boomers have houses. “
- Source: Surprise!
For our friends down south, the maximum payout (which I am assuming is following the same rules as in Canada)…
” In the United States where the maximum Social Security payment is $1,923 a month if you retire before age 63;
$2,533 if you wait until you’re 67 (if you were born in 1959 or later);
and $3,350 a month if you hang in until you’re 70. “
- Source: Surprise!
Sounds pretty sweet right?
That is, if you don’t croak before, and if you don’t factor in that you need to still qualify for Medicaid or some form of healthcare because you are sure to need it when you get older and if you don’t have any money to pay for it…… well you’re out of luck.
Of course to qualify for this max payout, you need to have been working for quite a while, not to mention requiring the support of all those illegal aliens working in the U.S. under fake (or real) Social Security numbers, paying into your retirement.
I also don’t think that those numbers are sustainable or realistic in the coming years, because it sounds.. impossible, but hey, with all the illegal aliens paying into the pot and not being able to collect one red cent, perhaps it’s true.

WE ARE ALSO ALL DYING SOONER & GETTING SICKER
I think they’re also saying that we are all dying sooner than we’ve expected (obesity, heart attacks, cholesterol, take your pick) and can expect to live our last 10 years in sickness, which makes healthcare in old age even more important, and it’s something that Americans don’t really have.
When you use up your body by cramming it full of junk food, ignoring your ballooning weight gain, or are in denial that you have a disease like type 2 diabetes that you have to take care of, your body starts to break down.
It is no longer a well-oiled machine because you’re not oiling it or using it judiciously, you’re pouring sludge into it and abusing it to the point where your organs start to give out and fail sooner than expected because you’ve exhausted their life spans.
Health is a lot more important than we all think.
To sum up health-related issues for our retirement: We simply aren’t taking care of ourselves which makes the situation worse, and we don’t even have money set aside to pay for it.
Case in point: My parents are house-rich, cash-poor but even that is not enough to pay for 10 years
(See Jane Savers? I DO read your requests!)
Basically, Garth is saying everyone is house-rich in Canada and cash-poor, which if my parents are of any indication, is absolutely true.
My parents are kind of in that awful range of Baby Boomers who haven’t done jack squat to save for their retirement for the past 40 years and even worse, can’t really seem to bring themselves to care as much as I think they should.
Before I came along last year, my mother couldn’t put her hands on $10,000 for an emergency.
My parents own (free and clear) a $500,000 home. If you ask my mother, she tells you it’s probably closer to $650,000 – $700,000 because it’s a detached home on a quiet street, because detached homes have been selling in that range in the past 5 years. I call that sheer delusion.
I tell her that her home is only worth what she would have to pay in rent if she didn’t own it, seeing as I am not convinced this house would sell for $700,000 with the lack (read: complete and utter absence) of maintenance and the horrible DIY crap my father has put into this place over the years.
To get this place into sellable condition, they would need to sink about another $30,000 – $60,000 to fix everything and redo everything he has touched. He has done so much “remodeling” in this poor house, that in hindsight he was better off just leaving everything as-is because now we have holes in the ceiling and in the wall from his projects.
THEY HAVEN’T SAVED MUCH LIQUID CASH
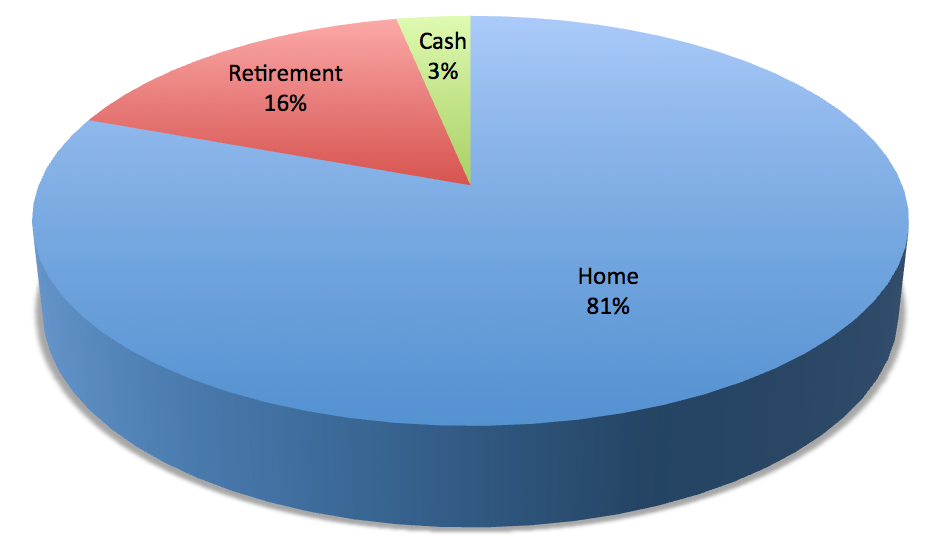
Aside from their home being their biggest and really, their only asset, how much do they have saved?
- Retirement Fund (Government): $100,000
- Cash: $20,000
Their net worth looks something like this based on my estimations:

The only thing that saves them is that my parents have a generous employer pension plan that kicks in when they decide to stop working, that gives them about $25,000 gross a year.
(Oh and I am not including the car that they own because frankly even though they paid $20,000 for it used, it can’t even sell for $5000 with the abuse my father has heaped on the car with his reckless and idiotic driving. No one in their right mind would buy this lemon with scratches and dents all over it.)
$25,000 a year doesn’t sound like much, but considering that she only started working about 10 years ago, this is not too shabby.
On top of that, they’re getting OAS and CPP to the tune of about $500 a month between the two of them, or $6000 a year (because they didn’t work most of their lives), all while my mother is still currently working at a $90,000 a year job.
So they pull in close to $100,000 in gross income between the two of them, with my mother earning the bulk — about 95% of that income. If she runs into a health problem now (heaven forbid) they are basically up the creek without a paddle.
They pretty much live paycheque to paycheque from what I can see, but my mother does at least try to save $1000 a month, however once she starts to see the balance add up, she gets the itch to spend it all, and it can be hard to rein her in when she sees pretty things.
My father? He’s just a wasteful, gambling-addicted, lazy, delusional degenerate. And I am being kind.

MY PARENTS CAN’T AFFORD TO CONTINUE LIVING THEIR $$$$ LIFESTYLE
The money flows out of their fingers and into any one of these pots:
- Gambling on lottery tickets at about $500/month for my father, about $100/month for my mother
- Eating out in restaurants costing $500/month at least
- Vacations costing $10,000 a year
- Food wastage as in they buy groceries and then it all goes rotten at about $200/month
Utter junk.
Now, keep in mind that I wouldn’t be calling ANY of that wasteful spending if they had a fully funded retirement fund and a set future ahead of them, because now they’re just enjoying their money even if they choose to waste it. In fact, they had a GREAT start at the age of 35 because my parents won the lottery.. but then they wasted most of it on themselves.
I call it utter JUNK because they DON’T have anything saved and are living as though they have millions stashed in the bank, when in reality they cannot sustain their current lifestyle without a $90,000 gross a year income.
Between OAS and CPP at $6000 a year, and my mom’s retirement plan at $25,000 a year, they can expect a gross income just barely above poverty level at $31,000 a year if she were to retire.
This is a far cry and a deep money drop from the $90,000 lifestyle they are used to.
Now do you understand why I am so stressed out sometimes?
THEY CAN’T SEE OR UNDERSTAND ANY OF THIS.
Let’s pretend they were to retire tomorrow: the only way they can survive for a little while longer, and live with that kind of generous $90,000 lifestyle is if they sell their home at $600,000 and live off that money for the next while.
Let’s say they end up with $450,000 net after having to fix up the home to undo all the crappy DIY jobs he did, pay realtor fees and so on, and they want to continue living that $90K lifestyle, gambling and wasting their money.
The math works out (with that $31,000 supplement from the government and her job), that they would blow through that money in a little over 7 and a half years.
Their house, once sold, would only help pay for 7.5 years in retirement.
.. but what if they live longer?
Until 90?
How the HELL are they going to pay for the last 10-15? I know that they think that we kids are their retirement plan, but I am not interested in enabling addicts.
BUT WHO AM I TO THROW STONES, YOU MIGHT SAY…
I haven’t worked in the past year or so (really, two years), and I am out there spending gobs of money on clothing and vacations as well.
The only difference between me and my parents is that all of my net worth is 100% mine, BF has his own savings as well which I do not track or disclose, but you can imagine that we aren’t in dire straits.
To top it off, I am also less than half their age.
I still have time (as I like to remind myself) to save for that eventual million or two when I retire, and while I do spend and enjoy my money, I am aware of what it is costing me.
Anyway, my point circles back to this:
Retirement is inevitable and coming, whether you want to pretend you have time ahead of you or not.
If you want to stop working ONE DAY and give your old, sick bones a rest, you need money to be able to do this.
So take stock of what you have today.
Make up your own net worth chart, and think carefully (long and hard) before putting everything you’ve got into a single fixed asset like a home, because eventually, you will need to retire and unless you sell that home, the capital is locked in there for good.
Otherwise, you will end up like my parents.
Oblivious until the storm hits and they realize that they have to take a $60,000 / year drop in spending because their income has been slashed by two-thirds.
Now, what do to about my parents?


